Executive summary
Philippine lawmakers are advancing a proposal to establish a unified excise tax rate for all nicotine-based e-cigarette products, targeting the current regulatory fragmentation between salt-nicotine and freebase formulations. The move, driven by concerns over illicit trade and market distortion, reflects growing regional momentum toward harmonized vaping taxation. If enacted, the policy would standardize tax treatment across product types, potentially reshaping retail pricing, compliance burdens, and supply chain dynamics across Southeast Asia’s second-largest vaping market.
Regulatory signal: A unified tax framework could reduce arbitrage opportunities between product types and strengthen enforcement capacity against illicit trade.
What happened
A joint committee of the Philippine House of Representatives is currently reviewing a draft bill that would impose a single excise tax rate on all nicotine-containing e-cigarettes, regardless of formulation—salt-nicotine or freebase. The proposal stems from findings that existing tax structures treat the two product types differently, with salt-nicotine products currently subject to lower rates in some provinces. This disparity has created incentives for cross-border smuggling and informal market circulation, particularly from neighboring jurisdictions with more lenient tax regimes.
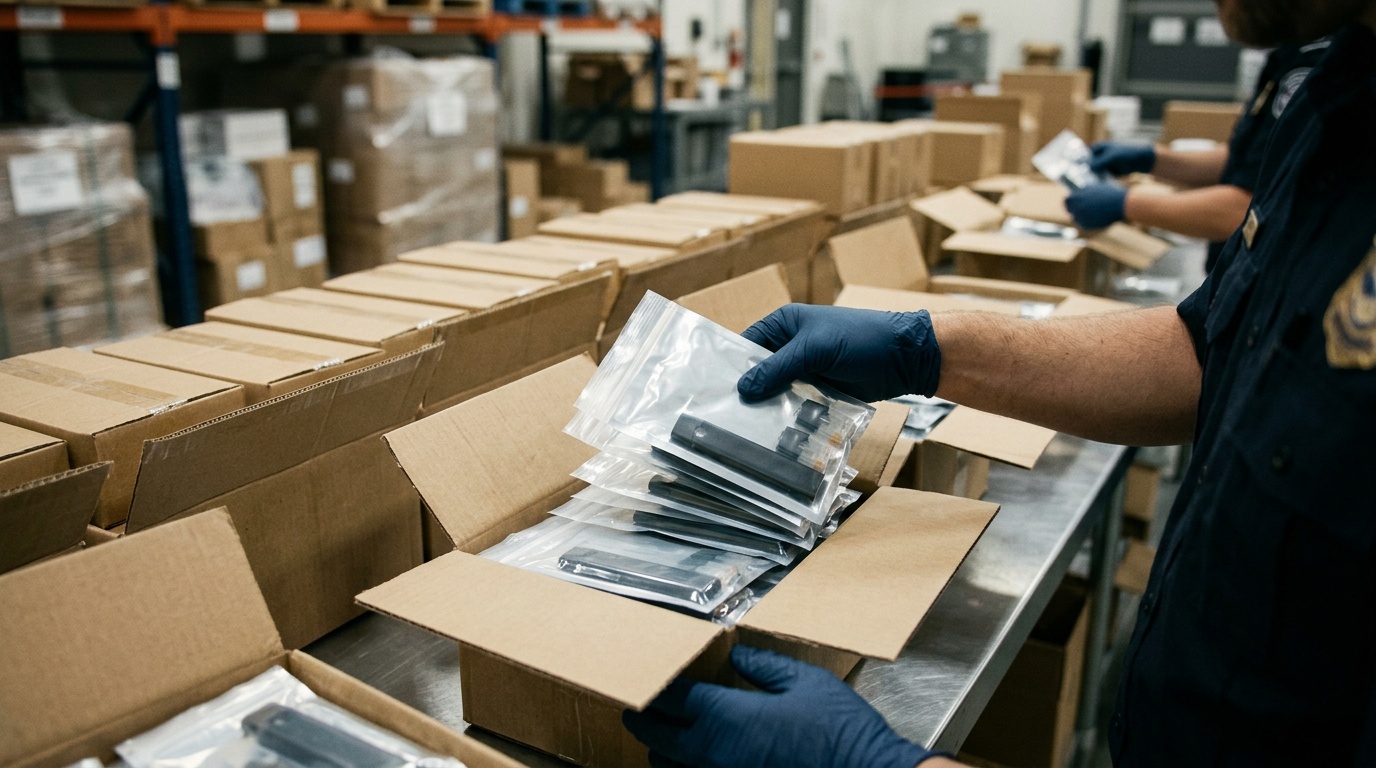
The committee’s assessment cites data from the Bureau of Internal Revenue (BIR) and the Philippine National Police’s Anti-Illegal Drugs Unit, which reported a 37% increase in seized vape products with mismatched tax stamps between 2023 and 2025. The draft bill proposes a tiered but unified rate based on nicotine concentration and product volume, with higher rates for concentrated liquids and disposable devices.
Why it matters
The proposed tax reform addresses a structural flaw in the Philippines’ current vaping regulatory architecture: the lack of product-type parity in taxation. By treating salt-nicotine and freebase products under the same rate, the government aims to eliminate price-based incentives for smuggling and informal distribution. This is particularly significant given the rapid growth of salt-nicotine products in the Philippine market, which have gained popularity due to smoother delivery and higher nicotine efficiency.
Without harmonization, tax differentials create regulatory arbitrage—where products are legally taxed in one region but smuggled into another with lower rates. This undermines state revenue, distorts market competition, and complicates enforcement. The proposed unified rate seeks to close this loophole while aligning with regional trends in Southeast Asia, where Malaysia and Thailand have recently moved toward similar tax consolidation.
Market impact
The proposed tax could significantly affect pricing and product availability across the Philippine vaping ecosystem. Retailers and distributors may face higher compliance costs as they adjust to a single tax framework, particularly if the new rate exceeds current effective rates for salt-nicotine products. This could lead to short-term price increases, especially for premium and imported brands.
However, the long-term impact may be stabilizing. A unified tax could reduce the prevalence of counterfeit and unregistered products, which currently flood the market through tax-avoidance channels. Manufacturers may also benefit from clearer rules, enabling better forecasting and investment planning. The policy could also accelerate the shift toward standardized product labeling and tax stamping, improving traceability and reducing the risk of non-compliant products entering the supply chain.
Market signal: Harmonized taxation may reduce illicit trade but could pressure margins for small distributors and independent retailers.
Regulatory impact
The move signals a shift toward more centralized and coherent vaping regulation in the Philippines. Currently, local governments have discretion in applying excise taxes, leading to a patchwork of rates and enforcement practices. The proposed unified framework would centralize tax authority at the national level, reducing jurisdictional fragmentation and improving auditability.
It also sets a precedent for future regulatory actions, such as standardized product testing, mandatory registration, and digital tracking systems. The BIR has indicated it may integrate the new tax with its existing e-commerce monitoring tools, which track cross-border digital sales and delivery logistics—key vectors for illicit vape trade.
Who is affected
- Domestic vape retailers: May face higher operating costs and compliance complexity, especially smaller outlets without automated tax systems.
- Importers and distributors: Will need to re-evaluate supply chain routes and pricing models to account for uniform national rates.
- Manufacturers: Both local and international brands producing salt-nicotine and freebase products will face equal tax treatment, reducing competitive advantages based on formulation.
- Regulators: The BIR and local enforcement agencies will gain stronger tools to track and penalize tax evasion and illicit trade.
- Consumers: May see price adjustments, particularly for premium or imported products, though long-term availability of legal products could improve.
Dawsen Take
The Philippines’ push for a unified vape tax represents a strategic effort to modernize its regulatory approach amid growing concerns over illicit trade and market fragmentation. By eliminating tax disparities between product types, the government is addressing a root cause of regulatory evasion rather than merely reacting to symptoms. This move aligns with broader regional trends toward tax harmonization and could serve as a model for other Southeast Asian nations grappling with similar challenges.
However, the success of the policy will depend on implementation. A poorly calibrated tax rate could inadvertently drive consumers toward the informal market, while inadequate enforcement infrastructure may limit the impact. The real test will be whether the new framework is paired with robust digital tracking, cross-jurisdictional coordination, and transparent compliance reporting.
What to watch
The next phase involves public hearings and stakeholder consultations, expected to begin in October 2026. Key indicators to monitor include: the final tax rate structure, the inclusion of digital tracking requirements, and the timeline for implementation. Additionally, watch for industry responses from major vape retailers and importers, as well as any legal challenges from distributors affected by the new rate. The outcome will signal whether the Philippines is moving toward a more regulated, transparent, and sustainable vaping market—or reinforcing existing enforcement gaps.
For more daily vaping news, check out dawsenai.com.
Original source: Filipino Lawmakers Weigh Unified Vape Tax
Written by
Comments