Executive summary
China’s Ministry of Finance and State Taxation Administration announced the removal of value-added tax export rebates for vape devices, nicotine, and related products effective April 1, 2027. The measure expands an existing policy that previously removed rebates for heated tobacco devices and nicotine-containing vaping products in April 2026. Export excise tax refunds and exemptions will continue unchanged.
What happened
The announcement adds four tobacco- and nicotine-related customs codes to the list of items ineligible for VAT export rebates. This includes code 8543400010, which covers vape devices and qualifying empty pods. The prior removal in April 2026 applied to code 8543400090, which industry sources associate with heated tobacco devices. The change takes effect after a six-month transition period.
Why it matters
VAT export rebates have historically lowered the effective cost of Chinese-made vaping products for international buyers. Their removal increases the landed cost of exports, potentially affecting price competitiveness in global markets. The policy shift reflects broader fiscal tightening around tobacco and nicotine products, aligning tax treatment with domestic consumption policies.
Market impact
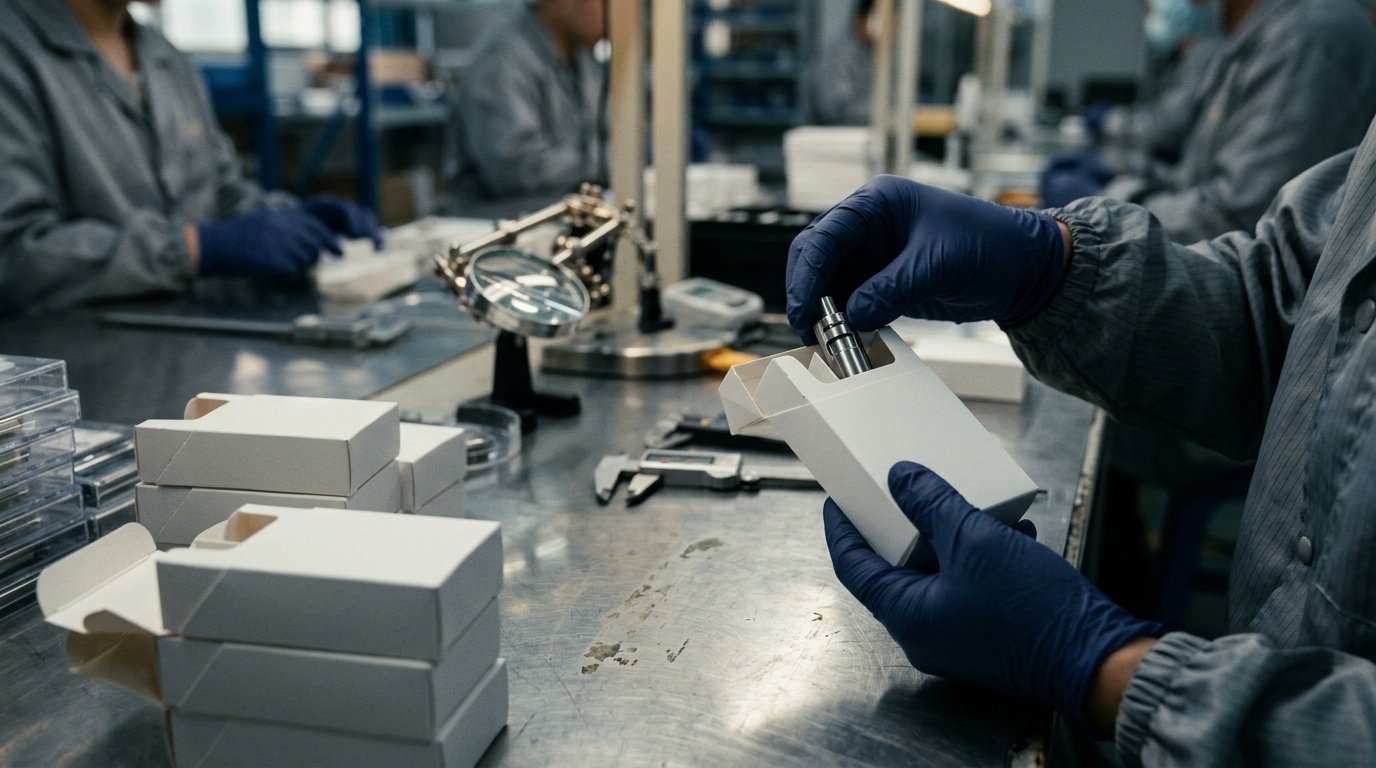
Chinese manufacturers dominate global supply chains for vape devices, pods, and nicotine ingredients. Higher export costs may pressure margins or lead to price adjustments for overseas customers. Some buyers could shift sourcing to other regions if cost differentials widen, though China’s scale and integration may limit immediate alternatives. The change adds to existing cost pressures from compliance, logistics, and regional taxation.
Market signal: The removal of VAT rebates raises baseline export costs for Chinese vape goods, testing the resilience of global supply chains dependent on Chinese manufacturing.
Regulatory impact
This move follows a pattern of reducing fiscal incentives for tobacco and nicotine exports, though it does not impose new restrictions or bans. It signals continued alignment of export tax policy with domestic regulatory trends, which have included flavor bans and youth access controls. No changes were announced to export excise tax treatment, which remains separate from VAT rebates.
Who is affected
Chinese exporters of vape devices, nicotine, nicotine salts, and certain non-combustible inhalation products will no longer receive VAT rebates on qualifying shipments after March 31, 2027. Importers and distributors outside China may face higher unit costs unless absorbed by suppliers. The policy does not apply to products under existing excise tax arrangements.
Dawsen Take
The policy reflects China’s ongoing recalibration of tax incentives for nicotine and tobacco-related exports, treating them increasingly like other regulated goods rather than export-promoted commodities. While not a direct ban or restriction, it adds fiscal friction to cross-border trade in vaping products. Operators should model the cost impact into 2027 pricing and supply contracts, particularly for long-term agreements.
Compliance watch: Firms with China-sourced vape inventory should verify customs code classifications and update accrual models for VAT liabilities beginning Q2 2027.
What to watch
Monitor whether other export incentives, such as tax exemptions or subsidies, are adjusted for vaping and nicotine products. Watch for potential ripple effects in Southeast Asian manufacturing hubs if cost differentials shift sourcing decisions. Track any updates to export excise tax policies, which remain unchanged for now but could be reviewed in tandem with VAT changes.
For more daily vaping news, check out dawsenai.com
For more daily vaping news, check out dawsenai.com.
Written by
Comments